What Is NOI in Real Estate? Net Operating Income Explained Simply
When you start poking around real estate listings or listening to real estate folks talk, you run into an alphabet soup of acronyms: ROI, IRR, Cap Rate, GRM, and NOI. Most of them are just fancy ways to slice and dice how much money a piece of dirt brings in.
Of all those acronyms, only one truly sits at the center of commercial and investment real estate: NOI, or Net Operating Income.
I have spent the last twenty-odd years buying and managing commercial properties across the Midwest—mostly larger industrial buildings, neighborhood retail strips, and apartment buildings. If an investor calls me asking whether a deal makes sense, I don’t ask what the asking price is, and I don’t ask what color the front doors are painted. I ask for the rent roll, the operating expenses, and the NOI.
If you don’t understand Net Operating Income, you cannot evaluate an income-producing property. Period. But the good news is that the math behind it isn’t complicated. If you can balance a household checking account, you can calculate NOI. Let’s break it down in plain English, with zero Wall Street jargon.
What Is Net Operating Income?
At its simplest, Net Operating Income is the total money a property generates from its normal daily operations minus the day-to-day costs required to run it.
Think of a property like a standalone small business. It takes in money from customers (tenants), and it spends money to keep the lights on, sweep the hallways, pay the county treasurer, and fix leaky pipes. Whatever cash is left over after those necessary operational bills are paid is your Net Operating Income.
Here is the basic formula:
Net Operating Income (NOI) = Realized Revenue – Operating Expenses
Notice what is missing from that equation. There is no mention of your mortgage payment. There is no mention of your income taxes. There is no mention of the money you spent replacing the entire roof. We will get into why those are excluded in a moment, but keep this in mind: NOI tells you how well the property performs on its own, completely separate from how you choose to pay for it.
Step 1: Calculating the Revenue Side
To find your NOI, you start at the top line: the money coming in the front door. Many novice investors make the mistake of taking the advertised rent, multiplying it by twelve, and calling it a day. In the real world, that almost never works.
Revenue consists of three distinct parts:
1. Potential Gross Income (PGI)
This is the theoretical maximum amount of money a property could produce if every single unit were occupied 365 days a year and every tenant paid full market rent on the first of the month. If you own a small four-unit apartment building where each unit rents for $1,200 a month, your Potential Gross Income is $4,800 a month, or $57,600 a year.
2. Vacancy and Credit Loss
Life happens. Tenants move out. Units sit empty for three weeks while you repaint walls and clean carpets. Occasionally, somebody loses their job and skips out on the last month’s rent. You must deduct a realistic estimate for vacancy and non-payment. In most stable markets, budgeting 5% to 8% for vacancy is prudent. If our four-unit building has an estimated 5% vacancy rate, you subtract $2,880 from that theoretical total.
3. Ancillary Income
Commercial and residential properties often make money from things other than base rent. This includes coin-operated laundry machines, paid parking spots, storage unit rentals, late payment fees, or pet rent. If your tenants pay an extra $1,200 a year combined for garage storage, you add that back in.
When you take Potential Gross Income, subtract Vacancy, and add Ancillary Income, you get your Effective Gross Income (EGI). That is the actual cash you realistically expect to collect.
Step 2: Subtracting Operating Expenses
Once you know how much money actually comes in, you have to pay the bills required to keep the building open and functional. These are your Operating Expenses (OpEx).
Legitimate operating expenses include:
- Property Taxes: The local government always gets its cut. In places like Ohio, Illinois, and Wisconsin, this can be one of your single biggest checks every year.
- Property Insurance: Hazard insurance, liability coverage, and flood insurance if applicable.
- Routine Repairs and Maintenance: Fixing a garbage disposal, replacing a cracked window pane, patching a minor drywall hole, or servicing an air handler.
- Property Management Fees: The fee paid to a management company to collect rent, field phone calls, and deal with maintenance. Even if you manage the building yourself, you should always include a 7% to 10% management fee in your math. Your time has value, and if you get hit by a bus tomorrow, someone else will need to be paid to run the place.
- Utilities Paid by the Owner: Water, sewer, trash collection, or common-area electricity for hallway lights and parking lot fixtures.
- Contracted Services: Lawn mowing, landscaping, pest control, and snow removal.
- Administrative and Marketing Costs: Advertising vacancies, accounting fees, and legal costs directly related to operations.
Add all those up, and you have your Total Operating Expenses.
What Does NOT Belong in NOI (The Common Traps)
This is where beginners get tripped up. There are several very real, very large checks you will write as an owner that must not be counted as operating expenses when calculating NOI. If you mix these up, your valuation numbers will be completely distorted.
1. Debt Service (Your Mortgage)
Your monthly mortgage payment—both principal and interest—is excluded from NOI. Why? Because a mortgage is a personal financial choice, not an operational feature of the building.
If an all-cash buyer purchases a strip mall, they have zero mortgage expense. If an aggressive investor buys the same strip mall with 90% leverage and a hard-money loan, their debt payments will be massive. The building operates identically in both cases: the tenants pay the same rent, the roof leaks the same amount, and the snow plow driver charges the same rate. NOI measures the quality of the asset, not the financing structure of the owner.
2. Capital Expenditures (CapEx)
There is a massive difference between a repair and an improvement. Patching a three-foot section of a roof is an operating expense. Replacing the entire roof with a new 30-year membrane for $25,000 is a Capital Expenditure. Upgrading an ancient boiler, paving a gravel parking lot with asphalt, or gut-renovating a kitchen are all CapEx.
CapEx items are major, infrequent investments that extend the useful life of the building. Accountants depreciate these costs over several years rather than deducting them immediately against operating income.
3. Depreciation and Amortization
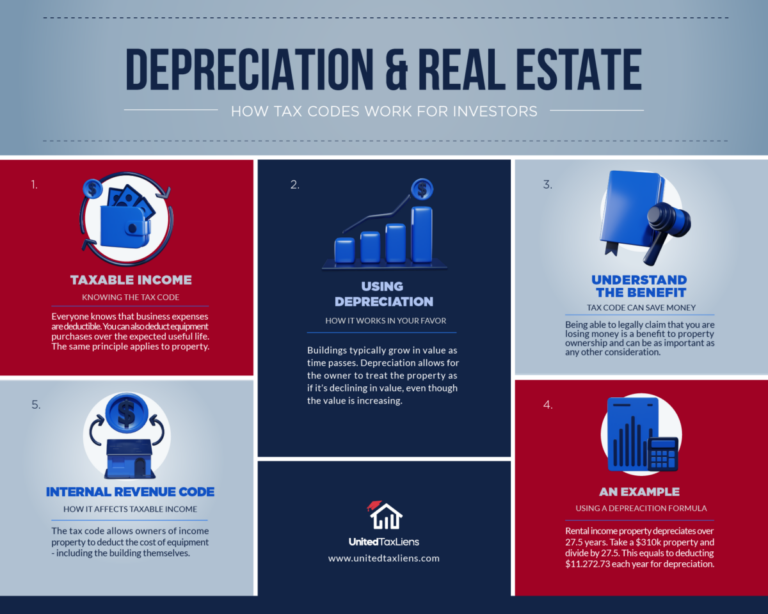
Depreciation is a non-cash tax deduction that the IRS allows you to take to account for the physical wear and tear of a building over time. It is vital for your annual income tax return, but it does not represent actual cash leaving your operational account this month. Therefore, it stays out of NOI.
4. Your Personal Income Taxes
What you owe the federal government at tax time depends on your personal tax bracket, your business structure, and your other write-offs. It has nothing to do with how the building itself runs.
A Realistic Real Estate Example
Let’s put real numbers to this so you can see how it works in practice. Suppose you are looking at a commercial property: a modest, single-story medical office building in an older suburb with three tenants.
The Revenue:
- Tenant A Rent: $2,500/month
- Tenant B Rent: $2,000/month
- Tenant C Rent: $1,500/month
- Total Monthly Scheduled Rent: $6,000
- Potential Gross Income (Annual): $72,000
- Less Vacancy & Credit Loss (7%): -$5,040
- Effective Gross Income (EGI): $66,960
The Operating Expenses (Annual):
- County Property Taxes: $8,500
- Property & Liability Insurance: $3,200
- Property Management (8% of collected rent): $5,357
- Lawn Care & Snow Removal: $2,400
- Common Area Electric & Water: $1,800
- Routine Maintenance Fund: $3,500
- Trash Removal: $1,200
- Total Annual Operating Expenses: $25,957
The NOI Calculation:
$66,960 (EGI) – $25,957 (Expenses) = $41,003 Net Operating Income
That $41,003 is the pure operational cash generation of the property. From that $41,003, you will make your annual mortgage payments to the bank. Whatever remains after the bank is satisfied is your true cash-in-pocket pre-tax cash flow.
Why Is NOI So Important?
You cannot buy, sell, or finance commercial real estate without knowing the NOI. It serves three critical functions:
1. It Determines the Value of the Property
Unlike single-family homes, which are valued based on what the neighbors’ houses sold for recently (comps), income properties are valued primarily on the income they produce. The tool used to convert income into value is the Capitalization Rate (Cap Rate).
The math is simple: Value = NOI / Cap Rate
If our medical office building has an NOI of $41,003 and comparable commercial properties in that town are trading at an 8% Cap Rate (0.08), the property is worth approximately:
$41,003 / 0.08 = $512,537
If you figure out a way to increase that NOI by $5,000—perhaps by appealing an inflated tax assessment or billing utilities back to tenants—you haven’t just made an extra $5,000 this year. At an 8% cap rate, you have increased the underlying market value of the building by $62,500 ($5,000 / 0.08).
2. Banks Use It to Decide if They Will Loan You Money
Lenders do not care how much you love a building. They care about the Debt Service Coverage Ratio (DSCR). The DSCR is simply the property’s NOI divided by its annual mortgage payments.
If a bank requires a 1.25 DSCR, it means the property’s NOI must be at least 125% of the annual mortgage payment. If your annual mortgage payments are $30,000, your property must produce at least $37,500 in NOI ($30,000 x 1.25) before the loan committee will approve your file. If your NOI drops below that threshold, the bank walks away.
Watch Out: How Sellers Try to Fake the NOI
Because higher NOI equals a higher sale price, sellers and their brokers have a natural incentive to make the NOI look as fat as possible. When you review an offering memorandum, look closely for these red flags:
- Unrealistic Zeroes: If you see $0 listed for property management because the current owner self-manages, plug in 8% to 10% immediately. If you see $0 for maintenance, run. The seller hasn’t fixed anything in three years, and you are about to inherit a mountain of deferred repairs.
- Yesterday’s Property Taxes: Brokers love to show the current property tax bill. But remember: when a property sells, the county often reassesses its value based on the new, higher purchase price. In year two of ownership, your tax bill can spike significantly, crushing your projected NOI.
- Capital Expenses Hidden in the Closet: Some sellers disguise recurring operational repairs as “one-time capital improvements” to artificially lower their listed operating expenses and inflate the NOI. Look at the general ledger, not just the seller’s summary sheet.
The Plain Money Takeaway
Net Operating Income is nothing more than total money collected minus the everyday costs of keeping the doors open. It ignores how you finance the building and what you owe the IRS.
When you evaluate any rental property, ignore the glossy photos and the optimistic sales pitches. Start with the verified income, subtract realistic operating expenses, and find the real NOI. If the NOI isn’t big enough to cover your mortgage with comfortable room to spare, it isn’t an investment—it’s an expensive lesson waiting to happen.
Keep reading: What Is a Cap Rate? A Beginner’s Guide to Real Estate Math, Cash-on-Cash Return Explained, and How to Analyze a Rental Property in 10 Minutes.